Chargeback Proof
How to cut chargebacks, win the disputes you cannot avoid, save your merchant account, and recover when it is taken away
Sound familiar?
You are probably here because one of these happened this week.
This book was written for exactly those mornings, by a merchant who has had all four of them more than once. It tells you what the bank is actually looking at, what to send, what not to send, and what to build so it stops happening.
The acquirer wrote to you about your ratio
They want a remediation plan in ten business days and you do not know what one looks like.
A reserve or a hold appeared
Ten or twenty percent of every settlement is being kept, or a batch is frozen “pending review”, and your cash flow just halved.
The account was terminated
There is a balance on hold for 180 days, you are probably on MATCH, and every new application is being declined.
A big chargeback arrived with a deadline
A four- or five-figure order, a reason code you do not understand, and seven days to respond.
The book
Twenty years on the wrong side of the dispute desk, written down.
Nobody explains chargebacks to you when you open a merchant account. You learn on a Friday afternoon, when the dashboard shows a balance you cannot withdraw. Chargeback Proof is the book the author wishes someone had handed him at the start: how the dispute system really works, why it is tilted against merchants, and the exact operating rules that keep a business inside the safe zone.
Part I explains the mechanism and the numbers: the ratio, the thresholds, the decline rate nobody watches, and the MATCH list. Part II is prevention: shipping, identity checks, dispute alerts, subscriptions, and the one-retry rule. Part III is what to do when a chargeback lands, with the representment structure that wins sixty to seventy percent of contested cases against an industry average of twenty to thirty. Part IV is disaster and recovery: the warning signs, what termination actually does, and how to come back.
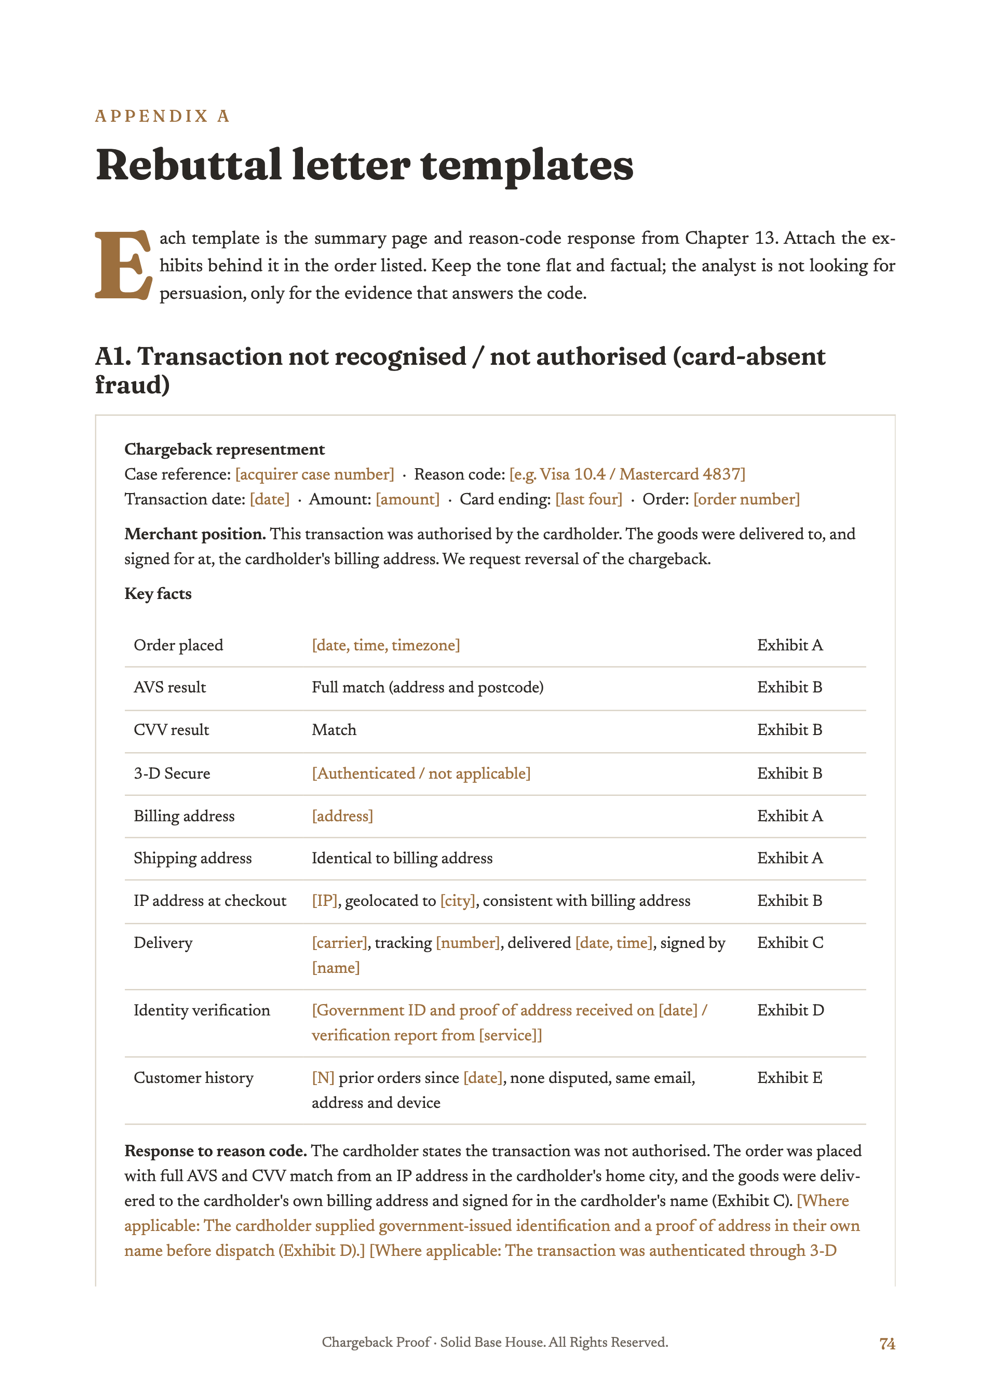
The appendices are the working tools: five rebuttal letter templates by reason code, seven customer email templates, reason-code tables for Visa, Mastercard, American Express and Discover, the checklists, a 30-day plan, and a glossary.
Who it is for
Anyone who takes card payments online: e-commerce owners, subscription businesses, high-ticket sellers, digital-goods merchants, and the people who run payments for them. It is most valuable to merchants who have already had a warning letter, a reserve, or a termination, and to anyone in a category the mainstream processors call high-risk.
What changes after you read it
Four things you will be able to do by next week
Know your real ratio and how far you are from the line
Both formulas, the acquirer’s hidden threshold, and the decline ratio that terminates accounts with almost no chargebacks at all.
Ship so that disputes cannot stick
Tracking, signature, billing-address-only, ID for high tickets, the split-shipment technique, and the evidence photographed before the box is sealed.
Answer a chargeback in a form the analyst rules on in four minutes
Summary page, reason-code response, exhibits strongest first. Templates for every common reason code.
Have a plan for the day the account is closed
Second processor, high-risk providers, the new-company route done so it holds, and how to get the reserve back.
Inside the book
Eighteen chapters and five appendices
- 01What a chargeback actually is
- 02Friendly fraud: the dispute that is not what it claims
- 03Why the deck is stacked against you
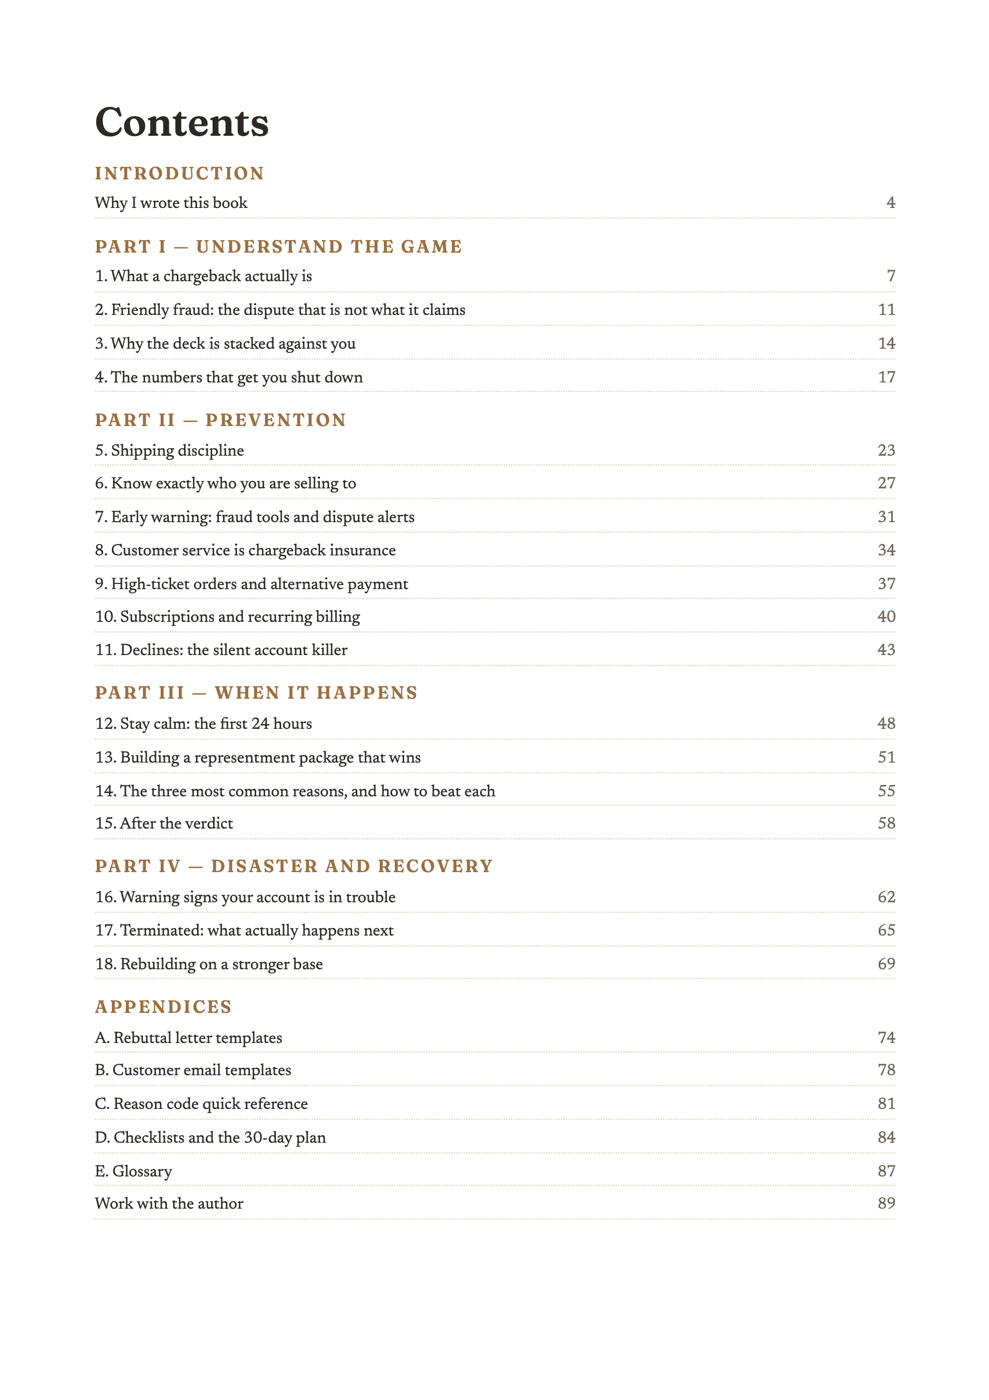
- 04The numbers that get you shut down
- 05Shipping discipline
- 06Know exactly who you are selling to
- 07Early warning: fraud tools and dispute alerts
- 08Customer service is chargeback insurance
- 09High-ticket orders and alternative payment
- 10Subscriptions and recurring billing
- 11Declines: the silent account killer
- 12Stay calm: the first 24 hours
Show all chapters and appendices
- 13Building a representment package that wins
- 14The three most common reasons, and how to beat each
- 15After the verdict
- 16Warning signs your account is in trouble
- 17Terminated: what actually happens next
- 18Rebuilding on a stronger base
- Appendix A · Rebuttal letter templates
- Appendix B · Customer email templates
- Appendix C · Reason code quick reference
- Appendix D · Checklists and the 30-day plan
- Appendix E · Glossary
- Work with the author
What a chargeback actually is
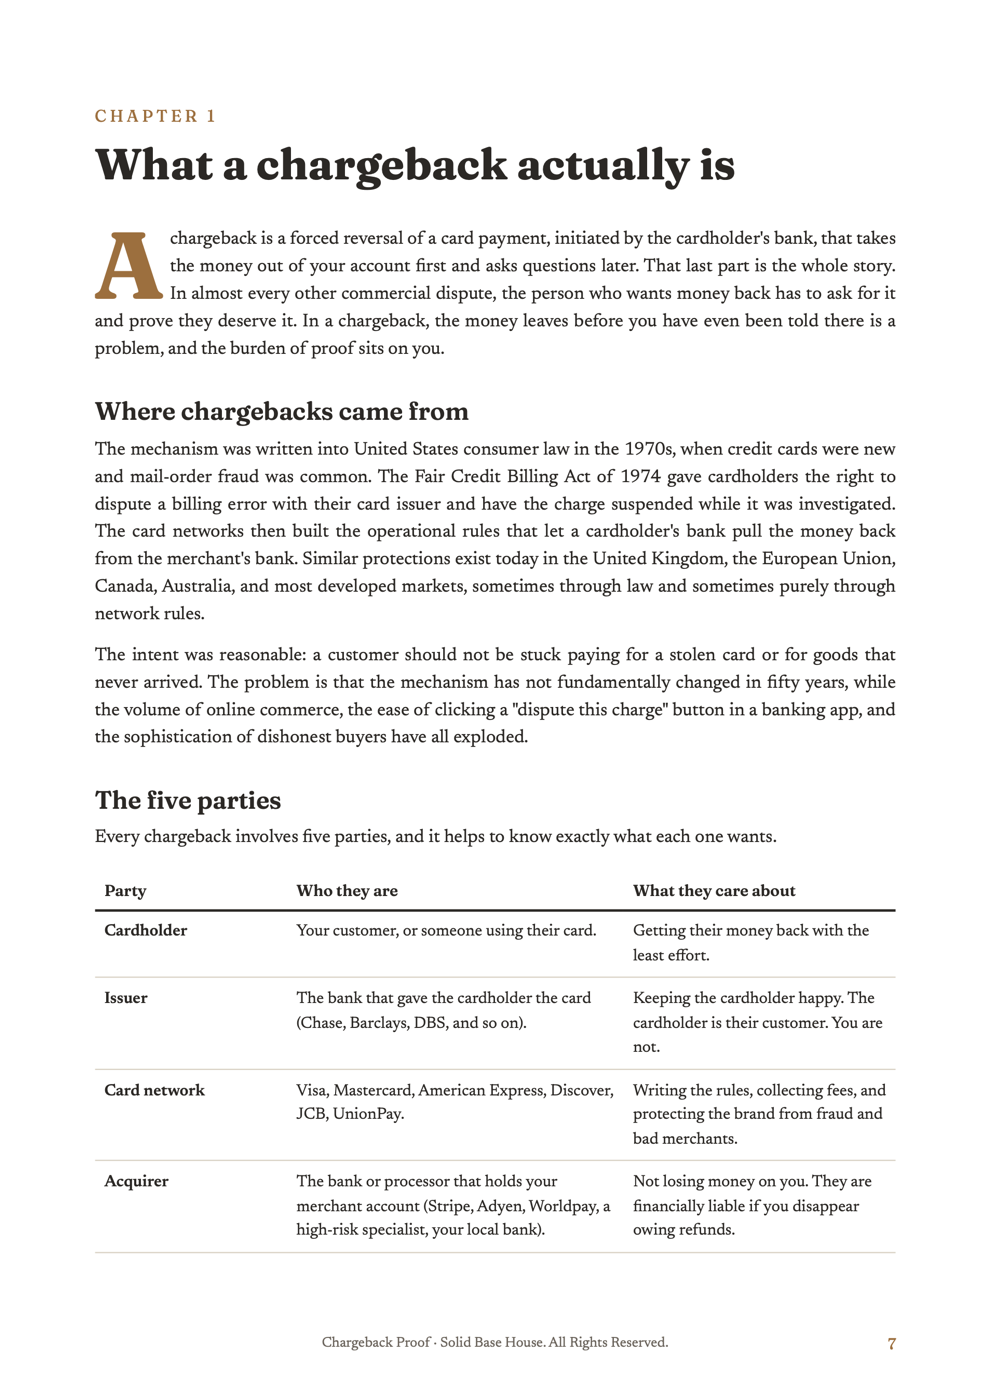
A chargeback is a forced reversal of a card payment, initiated by the cardholder’s bank, that takes the money out of your account first and asks questions later. That last part is the whole story. In almost every other commercial dispute, the person who wants money back has to ask for it and prove they deserve it. In a chargeback, the money leaves before you have even been told there is a problem, and the burden of proof sits on you.
Notice that only one party in that list is on your side, and even they are only on your side until you become a risk to them. The acquirer is not your friend. The acquirer is your guarantor, and guarantors watch you closely.
Get the book
Start with the free sample, or get the whole playbook now
Free sample
Free
The cover, the full contents, the introduction and all of chapter 1. No email required.
Download the free sampleThe complete PDF
US$99.99One payment. PDF, yours to keep.
All 18 chapters, all 5 appendices, every template. 90 A4 pages, typeset to read on a tablet or print. Delivered by email.
Buy the bookBook + 45-minute call
US$399
The PDF plus a private call with the author about your account, your ratio, or the dispute on your desk.
Book the callThirty-day guarantee
If the book does not give you at least one change that reduces your chargebacks or improves a dispute response, reply to the delivery email within thirty days and the price is refunded. Keep the PDF.
Ordering opens an email to us with the subject filled in. You receive a secure payment link and the PDF follows within one business day of payment.
Before you buy
Questions merchants ask
Is it specific to one processor or one country?
No. It covers Visa, Mastercard, American Express and Discover rules, with reason-code tables for each, and the acquirer behaviour that is the same everywhere. Examples are in US dollars; the thresholds and time limits are network rules that apply worldwide, with the regional differences noted.
I sell digital goods or subscriptions, not physical products. Does it apply?
Yes. Chapter 10 is entirely about recurring billing and the network rules for trials, reminders and cancellation, and the representment chapter covers usage-log evidence for digital goods.
My account has already been terminated. Is it too late?
Part IV is written for that situation: what happens to the held funds, what MATCH means, what not to do in the first week, and the legitimate routes back to processing, including the new-company route and high-risk providers.
Why US$99.99 for a PDF?
Because one avoided chargeback fee, one saved reserve month, or one won five-figure dispute pays for it many times over, and the twelve templates alone would cost more to have written. The thirty-day guarantee is there so the risk sits with us.
Can I get help with my specific case?
Yes. The last chapter describes the author’s consultancy: emergency termination response, remediation plans, done-for-you representment, MATCH strategy and prevention audits. Readers get the initial assessment call free.
When you need more than a book
Work directly with the author
Emergency termination response, the remediation plan your acquirer is asking for, done-for-you representment on high-value disputes, MATCH and new-account strategy, and prevention audits. Email a few lines about your situation and you will have an honest assessment, and a fixed quote if there is something to be done, within one business day.